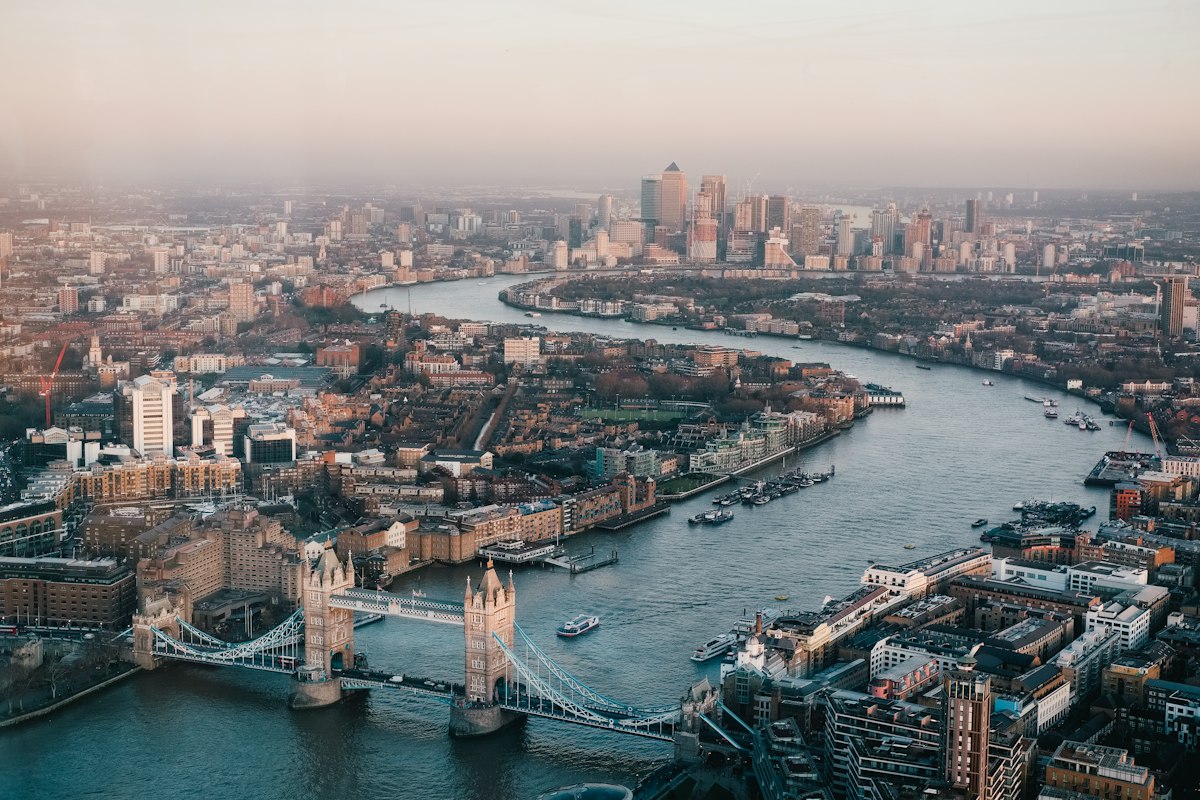
Moody's Ratings expects the outlook for UK life and property and casualty insurers to stay stable, with revenue holding up, but says weaker pricing and rising claims costs are likely to weigh more heavily on underwriting margins in 2027 while bulk annuity competition narrows life margins.
Moody's Ratings has told investors that the outlook for United Kingdom life and property and casualty insurers will remain stable, but that the profit picture is starting to change. According to Reinsurance News on October 8, 2026, in a report by Taylor Mixides, the agency expects revenue to hold up while margins come under pressure from weaker pricing and rising claims costs, particularly in 2027. A stable outlook is a statement about the direction of credit quality across a sector over the next twelve to eighteen months; it does not mean that every insurer will perform equally well, and it comes with caveats about where the pressure is likely to appear.
The economic backdrop set out in the report is subdued. Moody's forecasts UK growth of about 1.1 per cent in both 2026 and 2027, inflation that eases but stays around 3 per cent, and rising unemployment. Gilt yields have reached levels last seen in 1998, and 30-year yields are at multi-year highs, partly linked, the report says, to the conflict in the Middle East. For insurers, higher yields are a mixed development. They raise the income earned on new investments and make long-term guarantees cheaper to fund, but they can also reduce the market value of bonds already held and put pressure on capital if movements are sharp. The report notes that property and casualty insurers will feel higher yields sooner than life insurers because their portfolios are shorter in duration, so their investment income adjusts more quickly.
For life insurers, the main support is structural. Growth in workplace pensions and demand for pension risk transfer, along with the shift from defined benefit to defined contribution schemes, are expected to keep volumes healthy. Moody's gives the size of the defined contribution market as £0.8 trillion of assets under management at the end of 2024, and cites an estimate by Legal & General of about £1.5 trillion by 2034. Those numbers suggest the assets could nearly double in a decade, which is simple arithmetic from the two figures and is only an estimate by one firm. The challenge is that success attracts competition. Moody's says competition in bulk purchase annuities, in which an insurer takes on the pension obligations of a company scheme, is intensifying as more providers and capacity enter the market, and that this is narrowing margins on new business.
Two other points concern life insurers' investments and regulation. Some insurers are shifting toward government bonds and away from private credit, and Moody's notes that derivatives and repurchase agreements can help to improve returns but add liquidity risk. It also flags regulatory scrutiny of funded reinsurance, an arrangement in which an insurer transfers longevity risk and assets to a reinsurer, and sensitivity to credit defaults, interest rates, property valuations and credit conditions. The report cites the Financial Conduct Authority's Advice Guidance Boundary Review as a possible benefit for retirement products, although the coverage does not set out how.
The property and casualty section is more cautious. These insurers entered 2026 with relatively strong earnings, helped by reserve releases, favourable weather and lower reinsurance costs. In motor, the report says pricing pressure has eased as some insurers withdrew or consolidated, and that motor claims inflation has fallen to mid-single-digit levels. Moody's says this supports results as long as pricing stays disciplined. In home insurance, prices are still weakening, and commercial rates are falling faster amid ample capacity. The agency expects underwriting to stay healthy in 2026, but says the decline in pricing could weigh more heavily on margins from 2027. The mechanism is simple: when premiums fall while the cost of claims stays the same or rises, the gap that insurers earn from underwriting narrows.
Several cost pressures sit on the claims side. Vehicle technology is raising repair costs, and electric vehicles can be more expensive to fix, with battery damage increasing the likelihood that a car is written off. The Association of British Insurers reported a record £6.1 billion in property claims in 2025, including £1.2 billion from weather events, and Moody's warns that more severe weather could increase earnings volatility. Using the two figures, weather accounted for roughly one fifth of the record property claims total, though the report does not give the breakdown of the remainder. The Prudential Regulation Authority is placing more emphasis on reserving standards as pricing softens, a response to the risk that insurers could under-reserve to protect reported results when prices fall. Moody's also says that regulatory limits on risk differentiation and premium adjustments could make it harder for insurers to respond to claims inflation.
On capital, the picture is steady. Solvency ratios have fallen from their recent highs but remain robust. Moody's does not expect a significant near-term improvement because insurers are reinvesting surplus capital or returning it to stakeholders. In other words, the cushion that insurers built is not expected to grow, which makes it more important that underwriting results hold up.
What to watch over the coming year is the pace of price declines in commercial and home insurance, the evolution of bulk annuity margins as new entrants compete, the effect of regulatory scrutiny on funded reinsurance, and whether claims inflation in motor stays in the mid-single-digit range. The report suggests that the sector enters the next phase from a position of strength, but that 2027 is the year when discipline will be tested.
Key Points
- 1Moody's Ratings expects the outlook for UK life and property and casualty insurers to remain stable, with revenue holding up but margins under pressure from weaker pricing and rising claims costs, especially in 2027.
- 2The agency forecasts UK GDP growth of about 1.1% in both 2026 and 2027, inflation easing but staying around 3%, rising unemployment, and gilt yields at levels not seen since 1998.
- 3In life insurance, bulk purchase annuity competition is intensifying as more providers and capacity enter, narrowing margins on new business, while workplace defined contribution assets were £0.8 trillion at the end of 2024.
- 4In P&C, motor claims inflation has fallen to mid-single-digit levels, home prices are still weakening and commercial rates are falling faster amid ample capacity.
- 5The ABI reported a record £6.1 billion of property claims in 2025, including £1.2 billion from weather events, and the Prudential Regulation Authority is placing more emphasis on reserving standards as pricing softens.
Why This Matters
A stable outlook means Moody's does not expect rating pressure on the sector as a whole, but the report makes clear that the easy part of the cycle is ending. After a period of reserve releases, benign weather and cheaper reinsurance, insurers face softer prices just as repair and claims costs remain high, so underwriting discipline will matter more in 2027 than it did in 2025. For customers, softer pricing may mean lower premiums, particularly for businesses.
Related Stories

Allstate Reports $220 Million of September Catastrophe Losses, Taking Third-Quarter Losses to $1.65 Billion and Six-Month Losses to $3.4 Billion
October 26, 2026
FEMA Lets Homeowners Buy Flood Insurance Online Without an Agent as the NFIP Faces a December 12 Expiry
October 26, 2026

Victoria Gazettes Mandatory Five-Tier Flood Risk Ratings, and Insurers Say the Planning Rules Could Reshape Premiums Where Homes Are Built
October 26, 2026

Canada's Cyber Insurance Market Stabilizes After the Ransomware Peak, but the Insurance Bureau of Canada Warns of Shared-Vendor and AI Concentration Risk
October 26, 2026
Daily Intelligence
The PolicyRix Daily Brief
Get the day's key insurance and finance stories in one email, each linked to its original source. No spam. Unsubscribe anytime.
Informational newsletter only. Not financial advice. Disclaimer