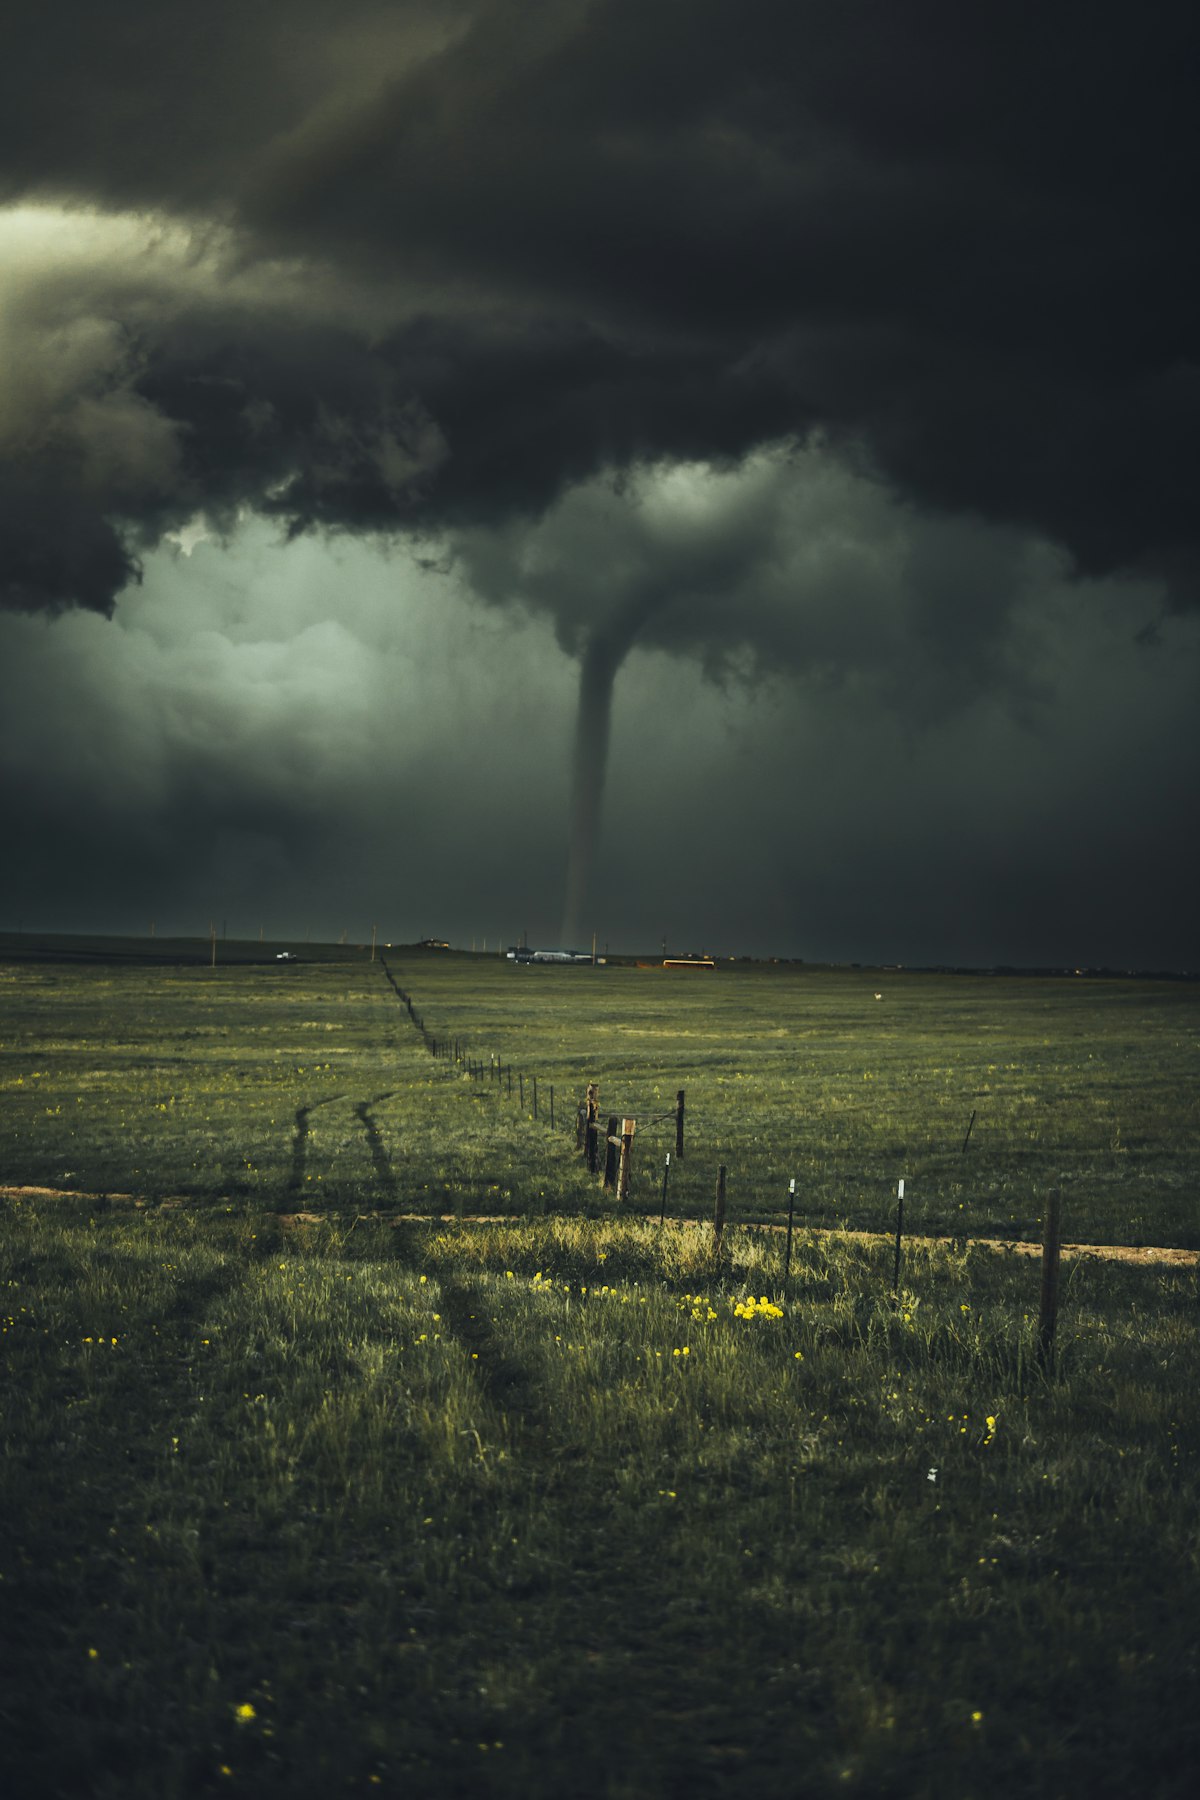
Estimates of insured losses from Hurricane Isaias, which struck the Florida Panhandle on October 9, 2026 as a Category 2 storm, run from Verisk's $1 billion to $2 billion to Moody's RMS's best estimate of $3.5 billion, while Florida regulators had logged 46,509 claims worth nearly $582 million by October 15 and AM Best calls it an earnings event, not a capital event.
Two weeks after Hurricane Isaias struck the Florida Panhandle, the insurance industry has a set of loss estimates that agree on the broad picture and differ on the details. The storm made landfall near Destin, Florida, at about 8:30 pm Central time on October 9, 2026, as a Category 2 hurricane with sustained winds of 105 mph, according to Insurance Business and Verisk. It was the ninth named storm of the 2026 Atlantic season and the first to reach hurricane strength, which Insurance Business describes as the latest first hurricane of a season on record. Isaias strengthened from a 40 mph tropical storm to a Category 3 hurricane with 120 mph winds before increasing wind shear weakened it ahead of landfall. Its track and relatively compact wind field limited exposure to the densely populated parts of the Gulf Coast.
The modelers' estimates, taken together, run from about $1 billion to $4.5 billion. Verisk reported on October 13 that insured onshore property losses would be $1 billion to $2 billion, covering wind and privately insured storm surge and saying wind will account for "the vast majority of losses." That estimate excludes flood losses paid by the National Flood Insurance Program, uninsured properties, infrastructure, boats, offshore assets, tornado damage and loss adjustment expenses. Cotality estimated $2 billion to $3 billion for wind and surge. Karen Clark & Company put privately insured losses at about $3 billion on October 15, covering residential, commercial and industrial property, automobiles and business interruption, and excluding boats, offshore property and NFIP losses; it compared the event with Hurricane Idalia in 2023, at about $3 billion, and Hurricane Ian in 2022, at an estimated $56 billion. On October 16, Moody's RMS gave a best estimate of $3.5 billion, with a range of $2.5 billion to $4.5 billion, covering wind, storm surge and flooding from rainfall, of which about $250 million is surge and inland flooding, including NFIP losses. Before the storm arrived, BMS Group had suggested $4 billion to $6 billion.
Why do the numbers differ? Mainly because of scope. Some estimates include tornadoes and inland flood, some exclude them, some count NFIP payments and some count only private insurance, and each model makes its own assumptions about how quickly demand for repairs inflates costs. The practical lesson is to read the footnote before comparing two figures. Gallagher Re, quoted by Insurance Business, expects total insured losses, including inland flooding, tornadoes and expected NFIP losses, to settle at the lower end of a low-to-mid single-digit billion-dollar range.
Claims data from the regulator give a more concrete view. Florida's Office of Insurance Regulation reported, as of October 15 and as described by the Florida Phoenix, 46,509 claims for residential, commercial, auto and other losses, with nearly $582 million of insured damage. About 87% of residential claims remained open with no payment made, and nearly 12%, or 4,773, were closed, 712 with payment and 4,061 without, with 3,319 of the homeowners claims closed without payment listed as closed for administrative reasons such as duplicates or claims opened in error. By county, Santa Rosa had 22,894 claims, Escambia 13,677 and Okaloosa 4,334. These are early reported claims, not final losses, and they do not capture everything the modelers count, such as business interruption that develops over time.
Individual carriers have given upbeat early reads. Beinsure reported that, as of Monday afternoon after landfall, People's Trust had about 400 claims, Universal about 3,000 and Security First about 300. In its third-quarter results published on October 22, Universal Insurance Holdings said claims activity so far was "less significant than initially anticipated." Selective's management said on its October 23 earnings call that it expects Isaias losses to be immaterial. Citizens Property Insurance Corporation, Florida's insurer of last resort, had about 8,800 policies in the 10-county Panhandle area when the storm hit and had received 860 claims by October 15, mostly residential, and AM Best said its exposure is much smaller than three years ago.
AM Best's assessment, reported by Insurance Journal, is that the hurricane will be an "earnings event" for insurers, meaning a hit to reported profit rather than a threat to capital. It said the hurricane is "not expected to significantly deplete surplus levels" and so should not trigger a surge in pricing. Moody's RMS said it expects the event's losses to be "manageable for the market," and noted that roof repairs and replacements after earlier storms, including Sally and Zeta in 2020 and Helene in 2024, likely improved the region's resilience to wind. Gallagher Re said current reinsurance capital makes an effect on the January 1 renewals unlikely, which fits with other signs this month, such as Gallagher Re's finding that global insured catastrophe losses for the first nine months of 2026 were the lowest since 2019.
The physical damage was concentrated. The worst impacts were in coastal Panhandle towns including Destin, Pensacola Beach and Navarre, where peak storm surge reached about 8 feet. Winds were strongest west of the eye, with winds of up to 117 mph reported around Pensacola, and the most severe wind damage was in Santa Rosa and northeastern Escambia counties. In Okaloosa County, trees falling on homes were the most common cause of damage. Vexcel counted about 17,860 damaged structures across Florida, Alabama and Mississippi, including 3,141 with major damage and 631 destroyed. Power outages affected more than 670,000 customers across four states according to Beinsure, and inland flooding stretched from Alabama to the Carolinas, with at least 21 tornadoes confirmed across the Southeast according to Insurance Business. Reports differ on the death toll, with Beinsure citing four deaths and the Florida Phoenix at least six in Florida.
For policyholders, three practical points follow from the coverage. Wind deductibles and named-storm deductibles will shape what insurers pay, and Insurance Business notes that whether a named-storm deductible applies to hurricane-spawned tornadoes depends on individual policy wording. Flood damage is paid by the NFIP or a private flood insurer, not by a standard homeowners policy. And the state has asked for about $237 million from the Federal Emergency Management Agency for debris removal and public infrastructure, a request that needs presidential approval, according to the Florida Phoenix. Final loss figures will take months to settle, and the numbers above should be read as estimates that are likely to move as claims are adjusted.
Key Points
- 1Hurricane Isaias made landfall near Destin, Florida on October 9, 2026 as a Category 2 storm with sustained winds of 105 mph, after peaking at Category 3 with 120 mph winds and weakening under wind shear.
- 2Modeler estimates differ: Verisk $1 billion to $2 billion (October 13), Cotality $2 billion to $3 billion, Karen Clark & Company about $3 billion (October 15) and Moody's RMS a best estimate of $3.5 billion within $2.5 billion to $4.5 billion (October 16), each with a different scope.
- 3By October 15 Florida's Office of Insurance Regulation had recorded 46,509 claims with nearly $582 million of insured damage, and about 87% of residential claims were still open with no payment made.
- 4AM Best expects an earnings event for insurers that should not significantly deplete surplus; Gallagher Re expects total insured losses at the lower end of a low-to-mid single-digit billion-dollar range and an unlikely effect on January 1 reinsurance renewals.
- 5Several listed carriers have said claims are lighter than first feared: Universal Insurance Holdings said claims activity is less significant than initially anticipated and Selective expects its Isaias losses to be immaterial.
Why This Matters
Hurricane loss estimates differ because each modeler counts different things, so a headline number can mean very different amounts of money. For homeowners and businesses on the Panhandle, the figure that matters is how quickly claims are paid, and the regulator's data show most residential claims were still open a week after landfall. For the wider market, the estimates suggest a manageable event: large enough to dent third-quarter or fourth-quarter profits at some insurers, but not large enough, in the view of the rating agency and the reinsurance broker quoted below, to change reinsurance pricing or threaten solvency.
Original Source
Insurance Business, Insurance Journal, Business Insurance, Beinsure and Florida Phoenix (October 13-19, 2026) ↗Related Stories
Munich Re Raises Its 2026 Profit Target to €6.6 Billion After a Preliminary €1.7 Billion Third Quarter Driven by Light Major Losses
October 24, 2026
Selective Insurance's Third Quarter: Operating EPS Up to $2.37 and a 96.8% Combined Ratio as Premiums Fall 7% on Deliberate Pruning
October 24, 2026

US Life Insurers' AI-Linked Investments Reach $85.2 Billion, Up 24% in Six Months, as Moody's Warns Its Figure Likely Understates the Exposure
October 24, 2026
France's October Riots Put Civil Commotion Cover to the Test: Insurers Face Up to €1.2 Billion and a State Backstop That Is Not Yet Live
October 23, 2026
Daily Intelligence
The PolicyRix Daily Brief
Get the day's key insurance and finance stories in one email, each linked to its original source. No spam. Unsubscribe anytime.
Informational newsletter only. Not financial advice. Disclaimer