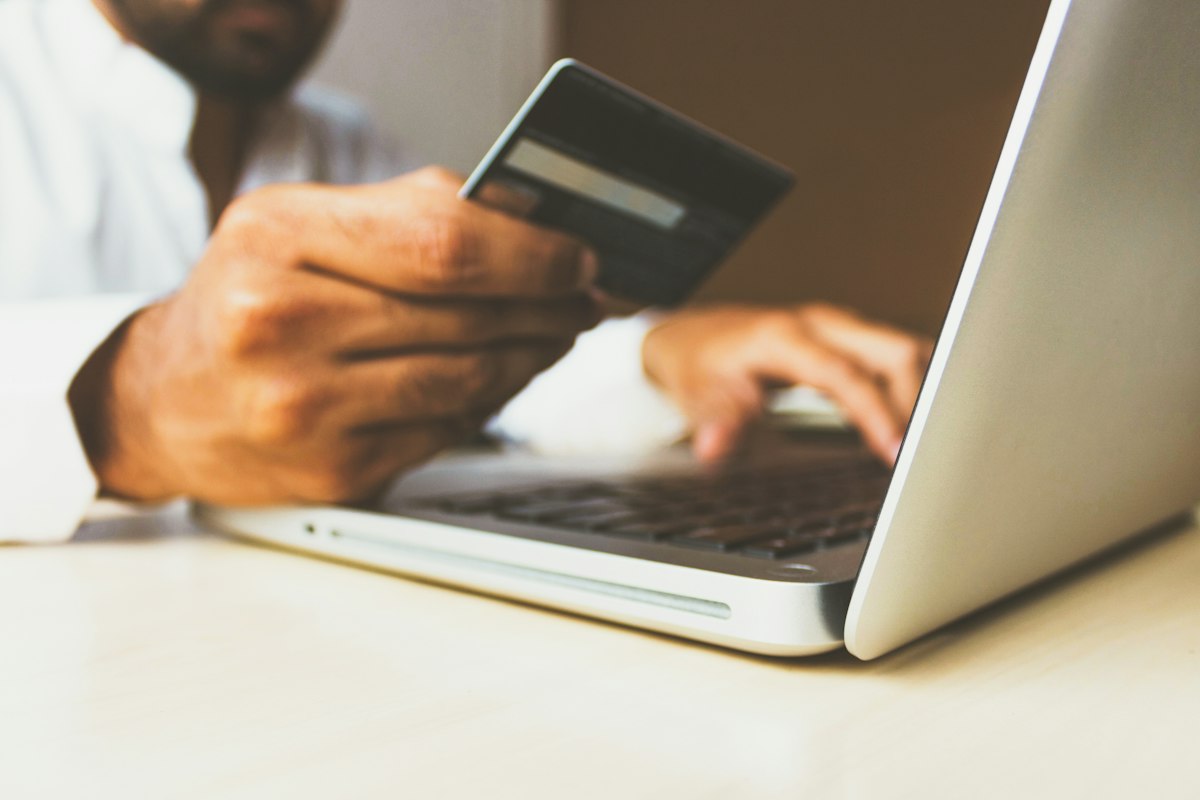
From July 15, 2026, UK interest-free 'Deferred Payment Credit' offered by a lender separate from the retailer is regulated by the FCA under policy statement PS26/1: lenders must check affordability, give key information, and customers can use the Financial Ombudsman and, in some cases, Section 75 refund rights.
Buy Now, Pay Later (BNPL), the interest-free instalment option that appears at online and in-store checkouts, has been brought inside the UK's financial regulation. The Financial Conduct Authority (FCA) calls the product Deferred Payment Credit, or DPC, and the new regime began on July 15, 2026. The FCA published its final rules on February 11, 2026, in policy statement PS26/1, after legislation was published in July 2025. According to analysis by the law firm A&O Shearman, the FCA made only minor amendments to its draft rules and guidance, which were set out in consultation paper CP25/23.
The scale of the market explains the interest. A&O Shearman's summary says the BNPL market grew from £0.06 billion in 2017 to over £13 billion in 2024. For years it sat largely outside consumer credit regulation, partly because interest-free, short-term credit was exempt.
What is covered? The FCA's consumer page explains that the regulated product is interest-free credit repayable in 12 or fewer instalments over 12 months or less. It is regulated when the lender and the supplier of the goods or services are different businesses, as is typical when a shopper uses a third-party BNPL provider at a retailer's checkout. Credit offered by the same business that is selling the goods is not regulated under this regime. Importantly, agreements taken out before July 15, 2026 remain unregulated, so the new protections do not apply retrospectively.
What must lenders do? According to the FCA, lenders must hold FCA authorisation or be registered under the temporary permissions regime to offer DPC. They must check that the customer can afford to repay before the agreement starts. A&O Shearman notes that lenders must assess creditworthiness for each DPC transaction, including those under £50, and that the FCA did not change the existing rules in its consumer credit sourcebook on this point. Lenders must give key information beforehand, including the amount to be borrowed, repayment dates and amounts, the late fee and the customer's rights and protections. If a customer misses a repayment, the lender must make contact and explain what it means, and must support customers who are struggling to repay.
The final rules softened some requirements. A&O Shearman reports that the amount of information in the key product information document was reduced: details on withdrawal, cancellation, early repayment, complaint rights to the Financial Ombudsman Service (FOS) and continuous payment authority move to "additional product information", although the key information must point customers to it. Lenders must tell customers whether they will, or may, check a credit reference agency before deciding on an agreement. Communications about missed payments need to explain the consequences arising from that missed payment, rather than every possible future consequence. Before terminating an agreement or taking enforcement action, firms must signpost free, impartial debt advice. Lenders no longer have to notify guarantors of missed payments. Unauthorised DPC lenders had to comply with the Consumer Duty by July 15, 2026.
One point that differs from the consultation concerns the Financial Ombudsman Service. A&O Shearman reports that the FOS voluntary jurisdiction does not cover DPC, contrary to what the consultation proposed, and that it excludes complaints before regulation began and activity from establishments in the EEA or Gibraltar. For consumers, the FCA's page says that if something goes wrong, they should complain to the lender first and, if unhappy with the response, can escalate to the Financial Ombudsman Service. The FCA also says people may be able to get a refund from the lender under Section 75 of the Consumer Credit Act, the same protection they would have when paying by credit card, subject to the conditions of that law.
The transition arrangements prevent a sudden gap in the market. Firms that were carrying on DPC as of July 15, 2025 without the necessary permissions could register for the temporary permissions regime during a notification window that ran from May 15 to July 1, 2026. Those firms then have six months after July 15, 2026 to apply for full authorisation. The FCA's page tells consumers to check lenders using the FCA Firm Checker, selecting "Borrowing money, including credit card lending and credit information", and says the temporary permissions list includes 15 lenders, such as Clearpay and PayItMonthly. The six-month window means those firms must apply for full authorisation by about mid-January 2027.
Consumers get a few practical benefits. They should see clearer information before they sign up, an affordability assessment that may sometimes lead to a refusal, and contact and support if they fall behind. For those in financial difficulty, the FCA directs people to MoneyHelper's Debt Advice Locator to find free local services.
Two limits are worth remembering. First, the regime covers interest-free credit from a separate lender; other types of credit, such as credit cards or loans, are already regulated through other rules. Second, because earlier agreements are outside the regime, someone who took out BNPL in June may not have the same rights as someone who took it out in August.
For retailers, the change matters indirectly. Some BNPL providers may tighten approvals as they implement affordability checks, which could affect conversion rates at checkout, though the sources reviewed do not quantify any such effect. For the market as a whole, the move from light-touch to full regulation is a significant step, and the FCA's decision to run a temporary regime shows it wants products to remain available while standards rise.
Key Points
- 1UK Buy Now, Pay Later, which the FCA calls Deferred Payment Credit (DPC), became regulated on July 15, 2026 under final rules published as PS26/1 on February 11, 2026.
- 2Regulated DPC is interest-free, repayable in 12 or fewer instalments over 12 months or less, and offered by a lender that is a different business from the supplier of the goods; agreements taken out before July 15 stay unregulated.
- 3Lenders must be FCA-authorised or in the temporary permissions regime, check that borrowers can afford repayments (including on transactions under £50), give key product information, contact customers who miss payments and support those in difficulty.
- 4Customers can complain to the lender and then the Financial Ombudsman Service, and may be able to claim a refund from the lender under Section 75 of the Consumer Credit Act.
- 5The FCA lists 15 firms in the temporary permissions regime, including Clearpay and PayItMonthly, and those firms have six months after July 15 to apply for full authorisation; the market grew from £0.06 billion in 2017 to over £13 billion in 2024.
Why This Matters
Millions of UK shoppers use buy now, pay later at checkout, often without thinking of it as borrowing. Regulation means these lenders now face affordability checks and customer-protection rules, and users gain routes for complaints and refunds, though agreements made before July 15 are not covered.
Original Source
Financial Conduct Authority (consumer BNPL page) and A&O Shearman (analysis of policy statement PS26/1) ↗Related Stories

Australia's Revised General Insurance Code Would Make Insurer Promises Legally Enforceable and Auto-Accept Home and Motor Claims After 12 Months, as AFCA Reports 36,022 Complaints
October 25, 2026
UAE's New Insurance Licensing Rules: Central Bank Circular 4/2026 Makes the Business Plan Central, Limits Foreign Insurers to Branches and Adds Personal Sanctions
October 24, 2026
Lloyd's of London's 2026 Half-Year Report: £3.5 Billion Profit, a 90.8% Combined Ratio and a Chief Executive Warning That Rates Are Past Their Peak
October 23, 2026
IRDAI's 'Recalibrating Economics of Insurance Distribution' Paper: Lower Expense Limits, Differentiated Commissions and a Three-Tier Distributor Structure, With Comments Due October 25
October 23, 2026
Daily Intelligence
The PolicyRix Daily Brief
Get the day's key insurance and finance stories in one email, each linked to its original source. No spam. Unsubscribe anytime.
Informational newsletter only. Not financial advice. Disclaimer