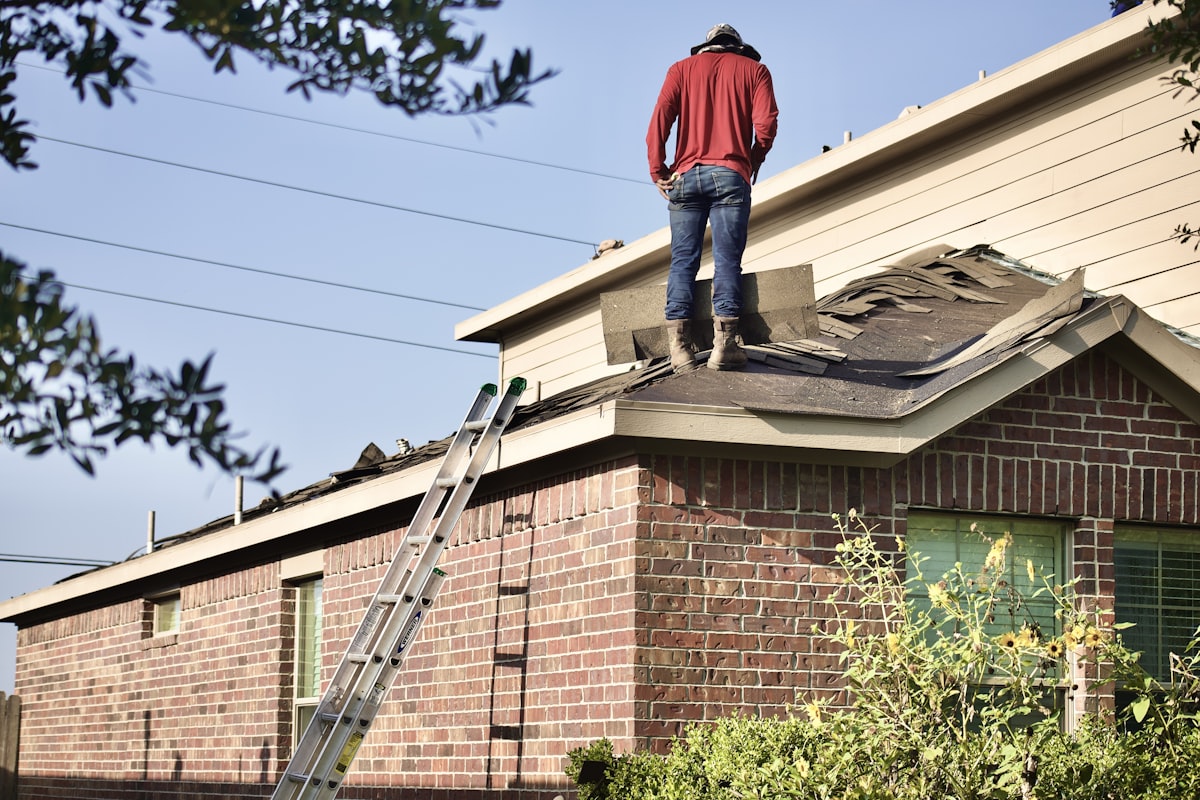
During National Roofing Week (June 7-13, 2026, run by the NRCA), Triple-I, IBHS and the US SBA highlighted roof upgrades, IBHS's FORTIFIED standard and SBA disaster-loan increases of up to 20% for mitigation.
A roof is the part of a building that takes the first hit from wind, hail and rain, and insurers and resilience groups say it deserves more attention. National Roofing Week 2026, which ran from June 7 to June 13, is organised by the National Roofing Contractors Association (NRCA), which says the week promotes public awareness of how essential roofs are, the positive contributions of the roofing industry, and the value of hiring a professional contractor. Within that week, the Insurance Information Institute (Triple-I) published a blog on June 8, 2026, by Loretta L. Worters titled "Partnering for Resilience: Protecting Homes Through Stronger Roofs," describing the shared view of Triple-I, the Insurance Institute for Business and Home Safety (IBHS) and the US Small Business Administration (SBA). This article summarises that blog and the NRCA information. An earlier version of this article said that Triple-I, IBHS and the SBA were running the week itself, and linked it to record severe-convective-storm losses. The week is run by the NRCA, and the blog does not give storm-loss statistics, so both points have been corrected.
What is the problem? The Triple-I blog says roof damage is a leading driver of insured losses and recovery costs. Water intrusion through a damaged roof can also destroy interiors, equipment, inventory and critical infrastructure, leading to business interruptions and financial hardship. For a household, that can mean displacement while repairs are made; for a small business, it can mean closing its doors. The blog does not give loss figures, and we do not supply any.
What do the experts recommend? According to the blog, stronger roofs can reduce damage, improve resilience and support long-term insurance affordability, and IBHS, Triple-I and the SBA are aligned on the idea that investing in resilience works. IBHS research links modest roof improvements to much lower storm damage and insurance losses. Examples include stronger deck attachments, sealed roof decks, impact-resistant materials, enhanced edge protection and better water barriers. These upgrades are most cost-effective when a roof is being replaced, because the work is already under way and the incremental cost is smaller than a separate project. A homeowner planning a re-roof can therefore ask the contractor which of these measures could be included.
What is FORTIFIED? IBHS's FORTIFIED programme is a voluntary construction and re-roofing standard that aims to close the gap between minimum building codes and true resilience. Codes set the minimum legal standard, which may not reflect the best available knowledge on storm protection. FORTIFIED goes further for roofs, and in some states insurers and governments recognise it through discounts or grants. The Triple-I blog does not list state programmes, and the availability and size of any discount vary by insurer and state, so homeowners should ask their insurers. Triple-I has also published separate material on state roof grant programmes.
What help is there for small businesses? The blog says small businesses are especially vulnerable and that upfront cost is a major barrier. It points to SBA financing, technical assistance and mitigation programmes. Specifically, SBA disaster loans can be increased by up to 20% for mitigation work, such as roof upgrades, and borrowers have up to two years from loan approval to request this funding. In other words, a business that borrows to repair damage after a disaster may be able to borrow somewhat more to rebuild in a stronger way. This is an existing programme, and the exact terms are set by the SBA, so businesses should check the current rules.
What other resources are listed? The blog lists Triple-I's Roof Toolkit, IBHS's Roofing Roadmaps, a National Roofing Week infographic, and a Triple-I article on how roofs affect home and business insurance. The page does not include details of insurer discounts.
Why does this matter for insurance? Roof age and condition are factors many insurers consider when deciding whether to offer cover and at what price. Some insurers have introduced special roof-related deductibles or limits on payments for older roofs, though the blog does not discuss these practices and they vary by company and state. A roof that is newer and built to a higher standard is likely to suffer less from storms, which benefits both the owner and the insurer. Whether this leads to a lower premium depends on the insurer and the location.
What can homeowners do? Inspect the roof regularly and after storms, keep records of repairs, and ask a licensed contractor about improvements when replacing it. Ask an insurer about the effect of roof age and materials on cover, and whether any discount applies for resilient roofs. Check local codes and permits. For small businesses, ask about SBA mitigation options before borrowing.
This article is general information drawn from published material by industry and trade groups, which have an interest in promoting roof investment. It is not a recommendation to buy any product or service.
Key Points
- 1The National Roofing Contractors Association runs National Roofing Week, June 7-13, 2026; Triple-I, IBHS and the SBA used it to promote roof resilience.
- 2Triple-I says roof damage is a leading driver of insured losses and recovery costs, and that water intrusion can also destroy interiors, equipment and inventory.
- 3IBHS research links modest upgrades, such as stronger deck attachment, sealed roof decks, impact-resistant materials, enhanced edge protection and better water barriers, to much lower storm damage; they are most cost-effective at re-roofing.
- 4IBHS's voluntary FORTIFIED standard aims to close the gap between minimum building codes and true resilience.
- 5SBA disaster loans can be increased by up to 20% for mitigation such as roof upgrades, and borrowers have up to two years from approval to request the funding.
Why This Matters
For many homeowners and small businesses, the roof decides whether a storm causes a small repair or a major loss. Better roofs can reduce damage and support insurance affordability, but upfront cost is a barrier.
Related Stories

Aflac's Third-Quarter Net Earnings Drop to $303 Million After $1.1 Billion of Portfolio-Repositioning Losses, While Adjusted EPS Edges Down 2.4% to $2.43 and Japan's Margin Narrows
November 5, 2026

Prudential Financial's Third-Quarter Adjusted Operating Income Falls to $1.32 Billion as the Prudential of Japan Sales Suspension Cuts Japan Earnings 25%
November 5, 2026

Lemonade's Third-Quarter In-Force Premium Jumps 34% to $1.55 Billion and Revenue Rises 73% to $336 Million, With the Net Loss at $43.7 Million and a Positive-EBITDA Quarter Promised for Q4
November 5, 2026

Corebridge Financial's Third-Quarter Operating EPS Rises 27% to $1.22 as the Share Count Falls 17%, With the Equitable Merger Reported to Be Making 'Significant Progress'
November 5, 2026
Daily Intelligence
The PolicyRix Daily Brief
Get the day's key insurance and finance stories in one email, each linked to its original source. No spam. Unsubscribe anytime.
Informational newsletter only. Not financial advice. Disclaimer