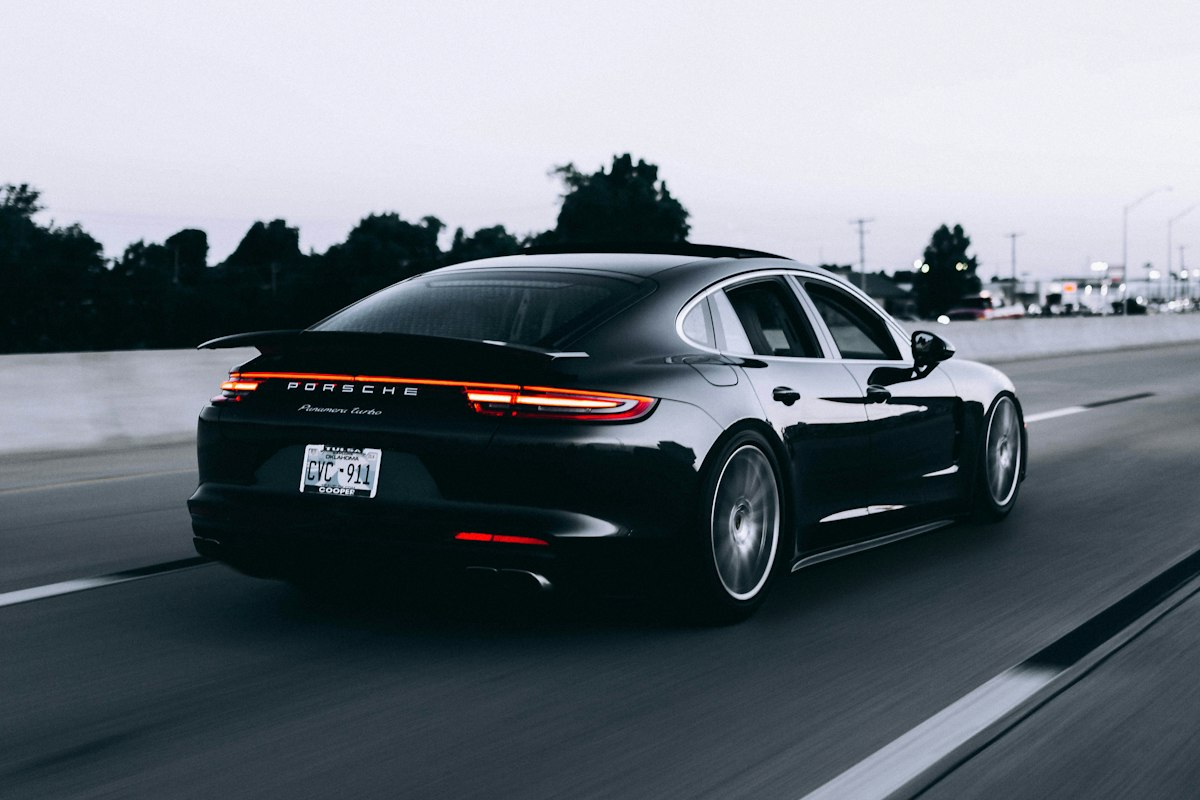
Insurify puts the average full-coverage premium at $2,237 a year at mid-2026, up 1% since the end of 2025, with Connecticut up 10% and 32 states expected to see year-over-year increases by December.
American car insurance prices have started to rise again after a year of declines, according to Insurify's mid-year report for 2026, though the national increase so far is small and the picture differs sharply from state to state. The figures were reported by Repairer Driven News and CollisionWeek on August 11, 2026. Insurify is an online insurance comparison company, and its numbers are based on the quotes it collects, so they describe the market it observes and not every policy in force. An earlier version of this article cited projections from a second company that could not be verified, so this version relies only on the Insurify report as described in the two trade publications.
Start with the national picture. Insurify says the average annual cost of full-coverage car insurance was $2,237 at mid-year, up 1% since the end of 2025. It projects that the average will reach $2,242 by the end of 2026, an increase of 1% over the year. That follows a 6% decrease in 2025, when insurers lowered rates and the average driver paid $140 less by year-end than twelve months earlier, according to Repairer Driven News. Insurify describes the change as a seven percentage point swing in the national trend. The earlier Insurify estimates reported in February used a different baseline, so figures should only be compared within the same report.
The number of states where prices are rising is the more telling change. In the first half of 2026, rates rose in 27 states, compared with nine states in the second half of 2025. Insurify projects increases in 32 states by the end of the year, with the largest expected in Connecticut at about 4% and West Virginia at about 3%. CollisionWeek notes that the steepest projected increase is in Connecticut, and that repair-cost inflation sits near the center of the reversal.
The largest first-half moves were in Connecticut, where the average rose 10%, or about $251 a year, the largest increase nationally. Kentucky rose 6%, West Virginia 5% and Illinois 4%. At the other end, Washington, D.C., New York and New Jersey each fell by at least 5%, and New Mexico, Massachusetts, Florida, Arkansas, South Dakota, Nebraska and Oklahoma saw decreases of between 2% and 5%. For the rest of the year, Insurify projects decreases of 1% to 3% in New Mexico, Arkansas, Minnesota, Colorado, Idaho, Texas, Oklahoma, Louisiana, Iowa and New Hampshire. The Repairer Driven News article also says residents in 39 states saw relief from rising premiums, but that figure overlaps with the 27 states reported above and may refer to a different measure, so it is not relied on here.
How expensive is it? Seven states and Washington, D.C. average more than $3,000 a year for full coverage. The five most expensive places named are Washington, D.C. at $3,880, Maryland at $3,646, Rhode Island at $3,611, Michigan at $3,229 and Georgia at $3,109. Those figures are averages for a standard driver profile in Insurify's data. Individual premiums depend on age, driving record, vehicle, location and coverage, and can be far higher or lower.
What is driving prices up? Insurify points to the cost of claims and repairs. According to the report, bodily injury claims rose 36% nationally from 2020 to 2024 and collision claims rose 42%, and the report links dense Northeast urban areas with more accidents and costlier claims. Auto maintenance and repair costs rose 45% over five years, roughly double the rate of general inflation. It also cites higher fuel prices, with gasoline rising from about $3 to about $4 a gallon, and says inflation hit a three-year high in May while consumer sentiment reached a record low. The coverage reviewed does not mention tariffs or vehicle theft as drivers, so this article does not attribute the increase to either. Other analysts have pointed to those factors in the past, but they are not part of this report as described.
Insurify's figures show a reversal: rates fell in 2025 and are now rising again in most states, with repair and claims costs cited as the main pressure. A rise of 1% nationally masks big differences, so a driver in Connecticut faces a very different market from one in New Mexico.
What can drivers do? Shop around at renewal, because rates vary widely between insurers for the same driver, and the insurer that was cheapest last year may not be now. Ask about discounts for bundling policies, safe-driving programs, low mileage and anti-theft devices. Review your coverage levels and deductibles, remembering that raising the deductible reduces the premium but increases what you pay after a claim. Keep a clean driving record and check your credit-based insurance score where it is permitted. Finally, avoid letting coverage lapse, since a gap can raise prices later and leave you exposed.
The year-end figure will show whether Insurify's projection of 32 states was accurate. If repair costs and claims keep rising, increases may spread. If competition and lower claims return, prices could stabilise. For now, the data suggest a slow upturn rather than a repeat of the sharp rises of 2022 to 2024.
Key Points
- 1Insurify's mid-year report puts the national average for full coverage at $2,237 a year, up 1% since the end of 2025, and projects $2,242 by year-end, following a 6% fall in 2025.
- 2Rates rose in 27 states in the first half of 2026, compared with nine states in the second half of 2025, and Insurify projects increases in 32 states by year-end.
- 3Connecticut had the largest first-half rise at 10%, about $251 more a year, followed by Kentucky at 6%, West Virginia at 5% and Illinois at 4%; Washington, D.C., New York and New Jersey each fell at least 5%.
- 4The most expensive places for full coverage were Washington, D.C. at $3,880, Maryland at $3,646, Rhode Island at $3,611, Michigan at $3,229 and Georgia at $3,109.
- 5Insurify cites repair and maintenance costs up 45% over five years, bodily injury claims up 36% and collision claims up 42% from 2020 to 2024, and higher fuel prices as cost pressures.
Why This Matters
After a year of falling prices, drivers in many states are seeing premiums rise again. Understanding what pushes prices up, and that changes vary widely by state, helps drivers decide when shopping around is worth the effort.
Related Stories

AM Best: Commercial Auto Liability Lost $6.4 Billion in 2024 as Litigation Costs Outpace 14 Straight Years of Rate Increases
October 25, 2026

Marsh Global Insurance Market Index: Commercial Rates Fall 5% in Q3 2026, the Ninth Straight Decline, as US Casualty Rises 6% and Pacific and IMEA Drop 12% and 14%
October 25, 2026
Hurricane Isaias Insured Loss Estimates Range From $1 Billion to $4.5 Billion: What the Modelers, Florida Regulators and AM Best Are Saying
October 24, 2026
Selective Insurance's Third Quarter: Operating EPS Up to $2.37 and a 96.8% Combined Ratio as Premiums Fall 7% on Deliberate Pruning
October 24, 2026
Daily Intelligence
The PolicyRix Daily Brief
Get the day's key insurance and finance stories in one email, each linked to its original source. No spam. Unsubscribe anytime.
Informational newsletter only. Not financial advice. Disclaimer